How Much Mortgage Can You Afford in Rwanda? A Practical Guide for Homebuyers
Learn how to estimate the mortgage you can comfortably afford in Rwanda by considering your income, deposit, existing debts, interest rate and repayment period.

Shafi Danny MUGABO
Writer
On this page14
- What Does Mortgage Affordability Mean?
- Start With Your Monthly Income
- Decide on a Comfortable Monthly Payment
- Subtract Your Existing Debt Payments
- Consider the Size of Your Deposit
- Understand the Effect of Interest Rates
- Consider the Repayment Period
- A Simple Mortgage Example
- Do Not Forget the Additional Costs
- Build an Emergency Fund
- Documents You May Need
- How to Improve Your Mortgage Affordability
- Get Prequalified Before Choosing a Property
- Make a Comfortable Decision
Buying a home is one of the largest financial decisions most people will make. Before searching for a property or applying for financing, it is important to understand how much mortgage you can realistically afford.
The amount a bank may approve and the amount you can comfortably repay are not always the same. A responsible budget should leave enough money for your normal living expenses, savings and unexpected costs.
This practical guide explains the main factors that can help homebuyers in Rwanda estimate an affordable mortgage.
What Does Mortgage Affordability Mean?
Mortgage affordability refers to the amount you can reasonably borrow and repay over an agreed period without putting excessive pressure on your monthly budget.
A lender may consider several factors when reviewing your application, including:
Your monthly income
Your employment or business income history
Existing loans and financial commitments
The value of the property
Your available deposit
The requested repayment period
The applicable interest rate
Your credit and repayment history
The property documents and valuation
Each financial institution has its own lending requirements. Meeting a general affordability estimate does not guarantee that a mortgage application will be approved.
Start With Your Monthly Income
Begin by calculating your reliable monthly income. This may include salary, business income, rental income or other income that can be documented.
If you are applying with a spouse or co-borrower, the lender may consider your combined eligible income, depending on its requirements.
Focus on income that is stable and can be supported by documents such as payslips, employment contracts, bank statements, business records or tax declarations.
Decide on a Comfortable Monthly Payment
As a personal planning guideline, you may consider keeping your mortgage payment within approximately 25% to 35% of your reliable monthly income.
This is not a universal banking rule. A lender may use a different calculation after considering your other debts, dependants and regular expenses.
For example:
With a monthly income of RWF 800,000, a cautious mortgage budget could be around RWF 200,000 to RWF 280,000.
With a monthly income of RWF 1,500,000, it could be around RWF 375,000 to RWF 525,000.
With a monthly income of RWF 2,500,000, it could be around RWF 625,000 to RWF 875,000.
With a monthly income of RWF 4,000,000, it could be around RWF 1,000,000 to RWF 1,400,000.
These figures are starting points for personal budgeting, not guaranteed loan limits.
Subtract Your Existing Debt Payments
Existing debts reduce the amount available for a mortgage. These may include personal loans, vehicle financing, salary advances, credit facilities or other regular repayments.
Suppose you earn RWF 1,500,000 per month and decide that RWF 500,000 is the maximum amount you can allocate to debt repayments. If you already pay RWF 150,000 toward another loan, only about RWF 350,000 remains within that budget for a mortgage.
Paying down existing debt before applying may improve your affordability and reduce pressure on your monthly finances.
Consider the Size of Your Deposit
The deposit is the portion of the property price that you pay using your own funds. The remaining amount is financed through the mortgage.
For example, if a property costs RWF 60,000,000 and you provide a 20% deposit:
Property price: RWF 60,000,000
Deposit: RWF 12,000,000
Mortgage required: RWF 48,000,000
A larger deposit reduces the amount you need to borrow. This can lower your monthly payment and the total interest paid over the loan period.
The required deposit varies by lender, mortgage product, applicant and property. Confirm the applicable requirement directly with the financial institution.
Understand the Effect of Interest Rates
The interest rate has a significant effect on your monthly instalment and the total cost of the mortgage.
Even when the loan amount remains unchanged, a higher interest rate produces a higher monthly payment. When comparing mortgage options, do not look only at the amount offered. Ask about:
The annual interest rate
Whether the rate is fixed or variable
How and when the rate can change
The total repayment amount
Processing and administration fees
Property valuation charges
Insurance requirements
Early repayment conditions
Penalties for missed payments
Mortgage rates and terms can change, so obtain a current written quotation from the lender before making a decision.
Consider the Repayment Period
Mortgages are normally repaid over several years. A longer repayment period may reduce the monthly instalment, but it usually increases the total interest paid.
A shorter repayment period normally means a higher monthly payment but a lower overall financing cost.
Choose a repayment period that balances a manageable monthly instalment with an acceptable total cost.
A Simple Mortgage Example
Assume you are considering a property priced at RWF 60,000,000 and have saved a deposit of RWF 12,000,000.
You would need a mortgage of approximately RWF 48,000,000.
Your actual monthly payment would depend on the lender’s interest rate, repayment period, fees and insurance requirements. Before proceeding, calculate different scenarios and determine whether the resulting payment fits your budget after your normal expenses and existing debts.
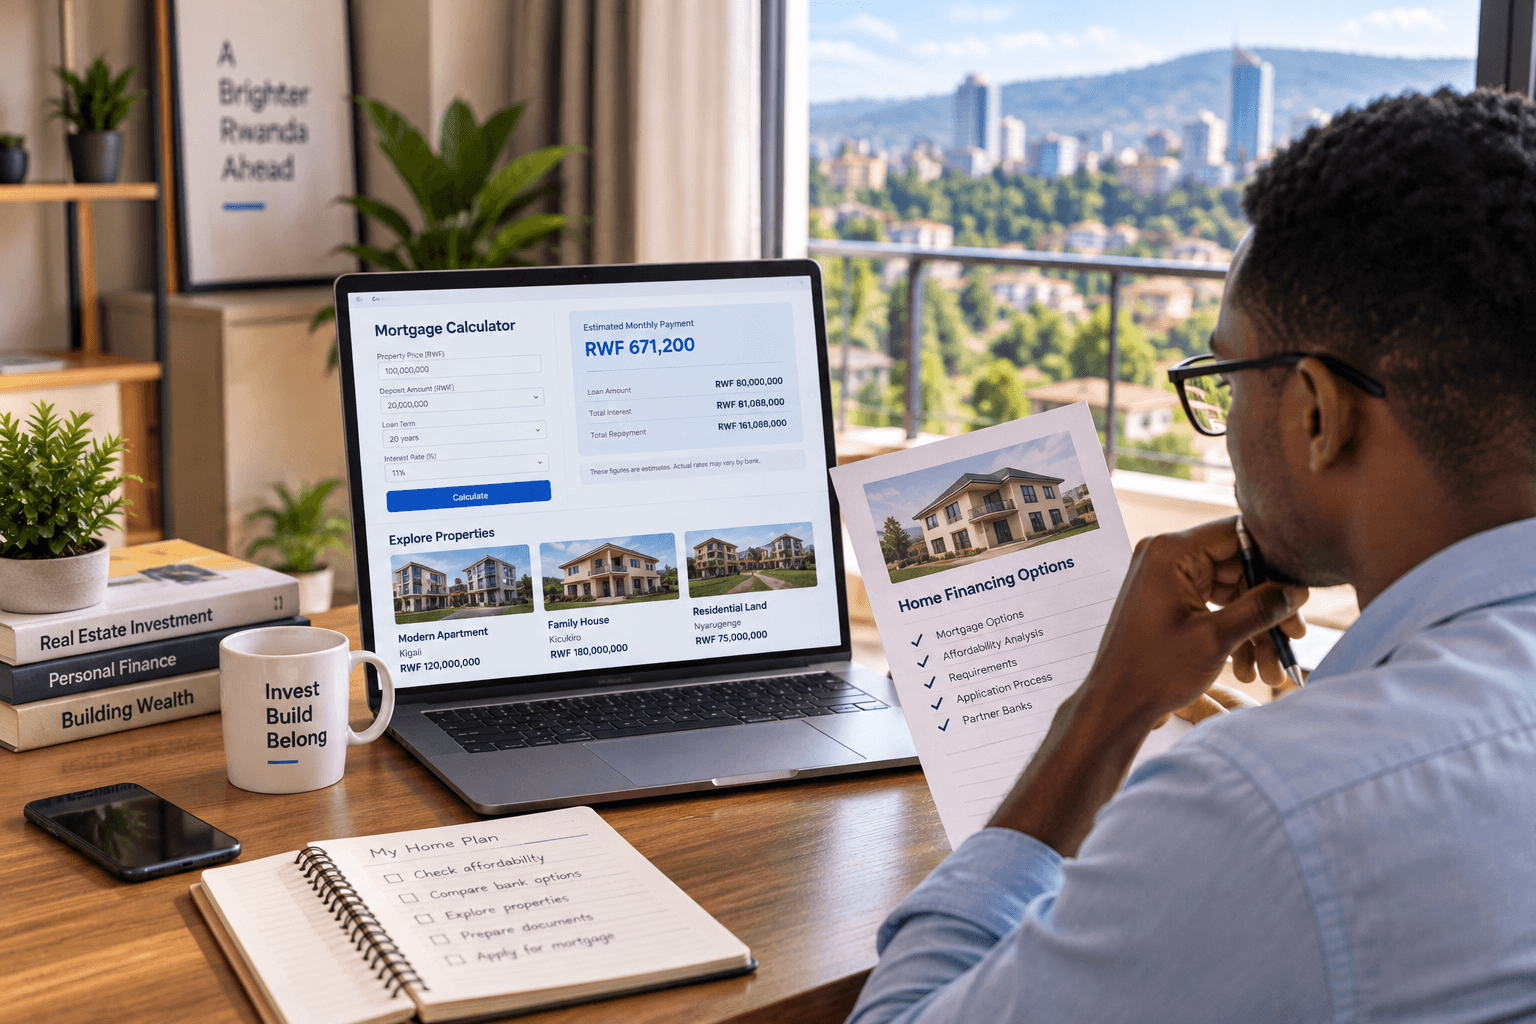
You can use the Nextline Homes mortgage calculator to compare loan amounts, interest rates and repayment periods.
Do Not Forget the Additional Costs
Your deposit and monthly mortgage payment are not the only costs involved in buying a home.
Depending on the transaction and financing arrangement, you may also need to budget for:
Property valuation
Legal and professional services
Loan processing fees
Property insurance
Mortgage-related insurance
Registration and administrative costs
Taxes or applicable government charges
Moving expenses
Immediate repairs or improvements
Future property maintenance
Keep part of your savings available for these expenses instead of using everything for the deposit.
Build an Emergency Fund
A mortgage is a long-term financial commitment. Your income or expenses may change during the repayment period.
Before taking a mortgage, consider keeping an emergency fund that can cover several months of essential expenses and loan payments. This can help protect you during a temporary loss of income, medical emergency or unexpected repair.
Avoid choosing a monthly payment that leaves no room for savings or emergencies.
Documents You May Need
Requirements vary by lender, but mortgage applicants may be asked to provide:
National identification or passport
Proof of income
Recent bank statements
Employment contract or employer confirmation
Business registration and financial records for self-employed applicants
Information about existing loans
Sale agreement or property information
Property valuation
Land title or ownership documents
Evidence of the available deposit
Applicants living outside Rwanda may be asked for additional documents relating to their foreign income, residence and source of funds.
How to Improve Your Mortgage Affordability
If the amount you can currently borrow is lower than the price of your preferred home, you can consider:
Increasing your deposit
Paying off or reducing existing debts
Choosing a more affordable property
Extending the repayment period carefully
Applying with an eligible co-borrower
Building a clearer income and savings history
Comparing mortgage products from different lenders
Avoiding new debt before applying
Focus on making the mortgage sustainable, not simply obtaining the highest possible loan amount.
Get Prequalified Before Choosing a Property
A preliminary mortgage assessment can help you understand the price range that may be realistic for your income and deposit.
Prequalification is not the same as final approval. The lender may still need to verify your income, review the property documents, complete a valuation and conduct other assessments.
However, starting the financing conversation early can prevent you from spending time on properties that fall outside your affordable range.
Make a Comfortable Decision
The right mortgage is one you can continue paying while meeting your normal living costs and preparing for the future.
Calculate your income, subtract existing obligations, consider your deposit and test different interest-rate and repayment-period scenarios. Compare offers carefully and request a clear explanation of every fee and condition before signing.
Explore mortgage options and use the mortgage and affordability calculators available through Nextline Homes to begin planning your property purchase in Rwanda.
This article provides general educational information and does not constitute financial advice, a loan offer or a guarantee of mortgage approval. Mortgage requirements, rates and fees vary between financial institutions and may change over time.